In the high-stakes world of venture capital, where firms often grow to hundreds of employees and manage dozens of disparate funds, Benchmark has long remained an outlier. With a 31-year history rooted in a small-partnership model, the firm has spent three decades resisting the industry’s trend toward bloat. Yet, even as the landscape shifts beneath their feet, the partners at Benchmark maintain that their core identity—a close-knit, agile, and hyper-focused team—remains unshaken.
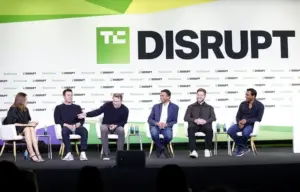
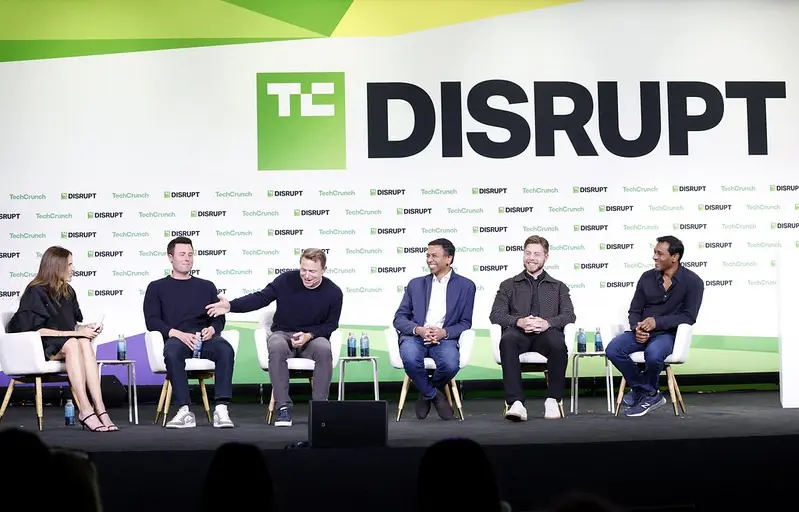
At this year’s TechCrunch Disrupt, the firm’s five general partners took the stage to address how they are adapting to a new era of capital intensity without losing the DNA that made them a legendary Silicon Valley institution. The conversation highlighted a firm in transition, balancing the necessity of scale with the stubborn refusal to abandon its fundamental principles.
Adapting to a New Economic Reality
The most visible change at Benchmark is the recent announcement of $2 billion raised across two funds. This marks only the second time in the firm’s three-decade history that it has significantly deviated from its traditional, smaller-vehicle structure. Peter Fenton, one of the firm’s veteran partners, addressed this shift with characteristic pragmatism.
"The craft that hasn’t changed is the core fund: working closely with founders at the beginning," Fenton explained. "It’s usually a 10-to-15-year commitment, working shoulder to shoulder, and that doesn’t scale."
Fenton acknowledged that for years, the firm maintained a $500 million core fund, a decision he now views as a "tactical error" that ignored the realities of economic inflation. The new, larger fund is a correction, intended to align with the current economy. Furthermore, the introduction of a dedicated growth fund represents a necessary expansion of their mandate. Previously, the firm’s early-stage focus meant missing out on significant opportunities that grew into massive enterprises. By creating a growth vehicle, Benchmark is now able to maintain its commitment to founders throughout their companies’ lifecycles, capturing value that was once lost to outside investors.
When asked about the strategy for this new $1.25 billion growth fund, Fenton emphasized the "agony and ecstasy" of a concentrated portfolio. "If the fund is successful, one or two investments will generate 90% of the returns," he noted, suggesting that the firm will likely make only four to eight bets from this vehicle.
The Power of a Small Partnership
For newer additions to the firm, such as Ev Randall, the draw of Benchmark is the antithesis of the "Byzantine corporate structures" found at larger rivals. Having worked at firms like Founders Fund, Bond, and Kleiner Perkins, Randall noted that the quality of a firm is defined by its people and the intimacy of their collaboration.
"You have to find people who you not only like but admire," Randall said. "That mix of attributes is very rare, and when I saw it, I immediately wanted to join."
Jack Altman, who joined the firm in February after a successful stint as an individual investor and founder of his own boutique fund, echoed this sentiment. Despite the allure of operating independently, Altman found the volatility of the current market—and the sheer pace of AI development—made the prospect of joining a collective of seasoned, like-minded investors highly attractive. "There’s no better place to learn," Altman remarked, noting that the firm’s lack of formal, bureaucratic processes is its greatest asset.
This informality extends to the firm’s famous Monday partner meetings, which famously have no agenda. While newcomers might initially feel the urge to impose structure, the partners argue that the lack of an agenda allows for a more fluid, organic, and reactive conversation. "It’s a decades-long conversation that only works if you’re small and actually enjoy spending time together," explained partner Eric Vishria.
The Ethics of Investment and Market Volatility
The conversation inevitably turned to the current AI landscape, characterized by intense competition and, occasionally, friction between firms. When asked about the "VC-founder pact" and the risk of backing competing companies, Vishria emphasized the importance of commitment. While he acknowledged that the rapid evolution of companies often leads to territory overlap, the firm prioritizes its relationship with entrepreneurs above all else.
"The harsh reality of this world is every company is evolving very quickly," Vishria said. "That commitment of exclusivity in that area is really important."
Addressing concerns about a potential market correction or "AI bubble," the partners remained skeptical of the doom-and-gloom narratives fueled by social media. They argued that many of the warning signs—such as the bankruptcy of Character.AI—are being misread by the public. According to Randall, the information environment has been warped by "hyperactive" echo chambers on platforms like X.
"Our companies see so much demand that they can’t get enough compute to serve customers who are willing to pay them at good gross margins," Randall noted. He suggested that if major players like OpenAI and Anthropic were to go public, it would provide the market with the transparency needed to dampen the current, unhealthy volatility caused by anonymous estimates and rumors.
The San Francisco Gravity Well
Despite the rise of remote work and the dispersion of tech talent, the partners remain convinced of the unique value proposition offered by San Francisco. While they concede that great companies can be built elsewhere—citing examples like Shopify—they observe a strong, persistent gravitational pull toward the Bay Area.
"Iron sharpens iron," Randall observed. "If you want to be around peers who are going to make you the best version of yourself, it’s hard to think of a city that does that better than San Francisco in the current era."
Fenton agreed, noting that the historical concentration of capital and talent in the region creates an "ecosystem effect" that is difficult to replicate elsewhere. Even founders who start outside of California often find themselves gravitating back to the city to open offices or spend significant time immersed in the local network.
As the discussion closed, it was clear that while the size of their funds may have changed, Benchmark’s philosophy remains rooted in the belief that venture capital is a craft, not a commodity. Whether they are debating the merits of hardware investments—as they did with Cerebras years ago—or navigating the complexities of the current AI boom, the partners view their roles as amplifiers of founder ambition. They are not interested in being "right" in a vacuum; they are interested in the long-term, arduous process of building companies that stand the test of time.
For Benchmark, the world may be moving faster, but the core of their business—high-conviction, concentrated bets made by a small team of partners who trust each other implicitly—remains the same as it was thirty years ago. In an industry increasingly defined by scale, their commitment to staying small feels, ironically, like their most significant competitive advantage.