The integration of blockchain technology into traditional finance has reached a critical juncture, as investors increasingly turn to tokenized stocks to gain round-the-clock access to global equities. However, a new study from the International Monetary Fund (IMF) suggests that while the demand for these digital assets is genuine, the infrastructure supporting them remains in a nascent, often fragmented state, leaving the market prone to heightened volatility and liquidity challenges.
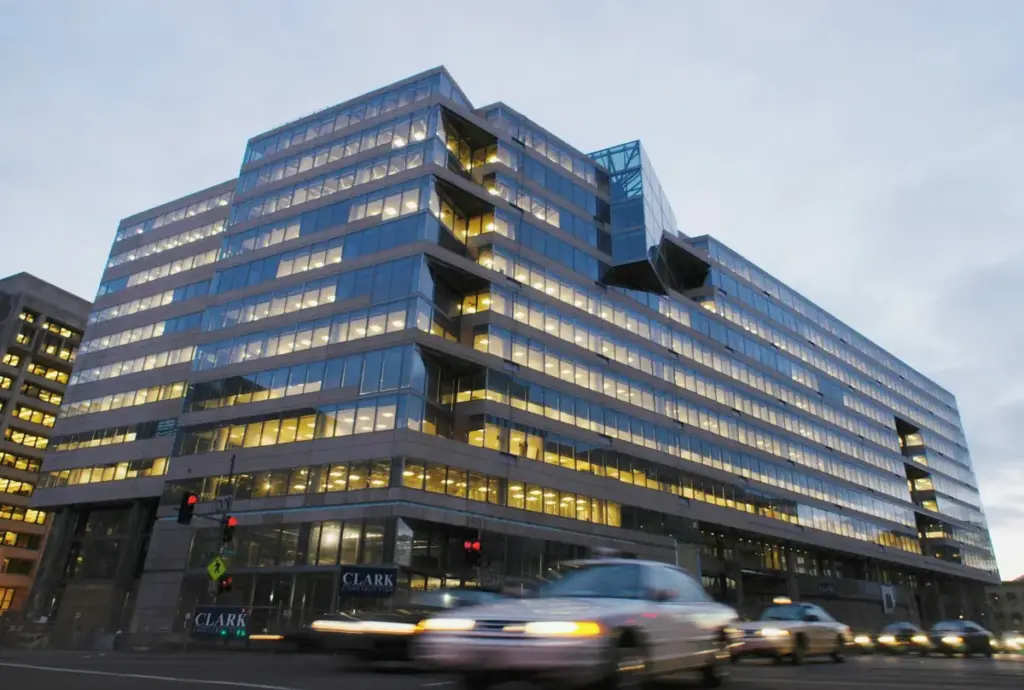
In its latest Global Financial Stability Report, titled "Scaling Tokenization: New efficiencies and new vulnerabilities," the IMF provides a comprehensive look at the state of the tokenized asset sector. The report focuses on the five most actively traded tokenized U.S. equities—including heavyweights such as Tesla (TSLA), Nvidia (NVDA), and Alphabet (GOOG)—as well as broader instruments like the Nasdaq 100 Index. By analyzing activity across both centralized and decentralized trading venues, the IMF has identified a clear shift in investor behavior, even as the broader financial establishment grapples with the implications of moving traditional securities onto a distributed ledger.
A New Frontier for Retail and Institutional Access
For many market participants, the appeal of tokenized stocks lies in their ability to strip away the limitations of the legacy financial system. The IMF study confirms that tokenized equities are already delivering on two of crypto’s most persistent promises: the ability to trade outside of standard market hours and the flexibility to purchase fractional shares.
The data underscores a clear appetite for these features. The IMF found that more than half of all trading volume for the tokenized assets analyzed took place outside of regular U.S. market hours. Furthermore, approximately 80% of these trades involved less than one full share. These findings serve as evidence that investors are prioritizing 24/7 accessibility and lower entry barriers, viewing the blockchain-based token not merely as a novelty, but as a functional tool for portfolio management that aligns with a modern, always-on investment landscape.
Beyond simple accessibility, the report reveals that these tokenized assets are beginning to serve as a reliable "price discovery" mechanism. The IMF observed that overnight price movements in tokenized stocks often contained valuable information regarding the underlying shares. Remarkably, once traditional U.S. markets opened, more than 85% of the price movement observed in tokenized shares overnight was reflected in their traditional counterparts within just five minutes. This tight correlation suggests that tokenized markets are becoming increasingly integrated into the global financial ecosystem, acting as a lead indicator for institutional traders.
The Scaling Challenge: Market Maturity and Liquidity
Despite the clear utility for investors, the IMF is cautious about the current state of the market. The report emphasizes that while the use case is compelling, the sector is still in its infancy. As of July 31, the total market for tokenized real-world assets (RWA) was estimated at approximately $65 billion. Within that segment, tokenized equities accounted for roughly $2.3 billion. When placed against the backdrop of the 2025 global equity market—which boasts a capitalization of just under $160 trillion, according to data from the Securities Industry and Financial Markets Association (SIFMA)—the scale of tokenization remains a tiny fraction of the global economy.
Gracy Chen, CEO of Bitget, highlighted the disconnect between the promise of the technology and its current implementation. "Moving assets onchain is only the first step," Chen noted. "The bigger question is how efficiently that capital can work once it is there."
The efficiency gap is largely attributed to the fragmentation of the current landscape. The IMF points out that the market is split across an array of private platforms, public blockchains, and varying custodial and settlement tools that often lack interoperability. Without a unified system, tokenization struggles to deliver the promised savings in cost and time that distributed ledger technology is theoretically capable of achieving.
Moreover, the report highlights a significant disparity in market quality. Tokenized stocks were found to be approximately 1.5 times as volatile as their equivalent shares on traditional venues and significantly less liquid. This lack of liquidity, combined with the inherent volatility of the crypto space, presents a hurdle for institutional investors who require deep, stable order books to manage large positions without causing excessive slippage.
Regulatory and Systematic Risks
The expansion of the tokenized market is accelerating, even as the IMF issues its warnings. The sector has seen a surge of activity in recent months. Bullish (BLSH), a Gibraltar-based exchange and the parent company of CoinDesk, launched its tokenized equity trading service in August. Similarly, major industry players, including Coinbase Global (COIN), Kraken, Binance, and Robinhood Markets (HOOD), have all established their presence in this space.
The momentum continues to build at the institutional level. Earlier this month, OKX and the Intercontinental Exchange (ICE)—the parent company of the New York Stock Exchange—filed plans for a new venue designed to facilitate round-the-clock tokenized trading of U.S. stocks. This move signals that traditional financial giants are increasingly comfortable with the idea of migrating core equity trading to blockchain-based infrastructure.
However, the IMF warns that the transition to these automated systems carries inherent risks. While tokenization offers the potential to automate complex processes—such as dividend payments, the reconciliation of records, and the acceleration of collateral transfers—it also introduces new vulnerabilities. The combination of automated margin calls, the rapid movement of collateral between platforms, and the non-stop nature of 24-hour trading could, under the right conditions, make a market shock significantly harder to contain.
The current risks remain relatively muted simply because the total volume of tokenized assets remains small. However, the IMF’s report serves as a formal call to action for regulators and market participants alike. It argues that for this technology to reach its potential without destabilizing the broader financial system, significant groundwork must be laid.
Specifically, the report calls for the development of clear legal rules regarding ownership, the establishment of robust safeguards to ensure market liquidity, and the creation of standardized links between disparate settlement systems. As the market for tokenized equities grows, the current reliance on fragmented, proprietary systems will likely become untenable. Without a cohesive framework that addresses how assets are settled, governed, and protected, the transition to a blockchain-based equity market may prove to be a source of instability rather than the promised evolution of modern finance.
The IMF’s message is clear: the technology works, and the demand is real, but the bridge between the legacy system and the digital future is still under construction. Until legal, technological, and liquidity standards are harmonized, the market will likely remain a specialized venue for early adopters rather than a pillar of the global financial infrastructure.