







As the promise of lucrative yields from restaking has largely evaporated and the specter of smart-contract vulnerabilities continues to loom over the decentralized finance (DeFi) landscape, Ethereum’s most prominent liquid restaking protocol has made a definitive break from its origins. By the conclusion of the current quarter, ether.fi will have effectively severed the last structural ties between its flagship staking tokens and the EigenLayer ecosystem.
According to internal protocol documentation, less than 1% of the assets under the protocol’s management remain restaked as of August. The company has confirmed that it plans to finalize the removal of EigenPod withdrawal credentials by the end of the year, signaling the end of an era for a project that was once the face of the restaking craze.
When ether.fi first burst onto the scene in 2024, its value proposition was clear and aggressive: user deposits were automatically restaked on EigenLayer, allowing participants to maximize their capital efficiency. However, the tides turned in August when the firm made the strategic decision to strip restaking functionality from weETH—its primary token, which had become widely accepted as collateral across the DeFi ecosystem. This move effectively returned the token to its roots as a standard liquid staking asset. For users still seeking the specific exposure offered by restaking, the protocol now mandates a shift to a separate, distinct token built on the rival platform, Symbiotic.
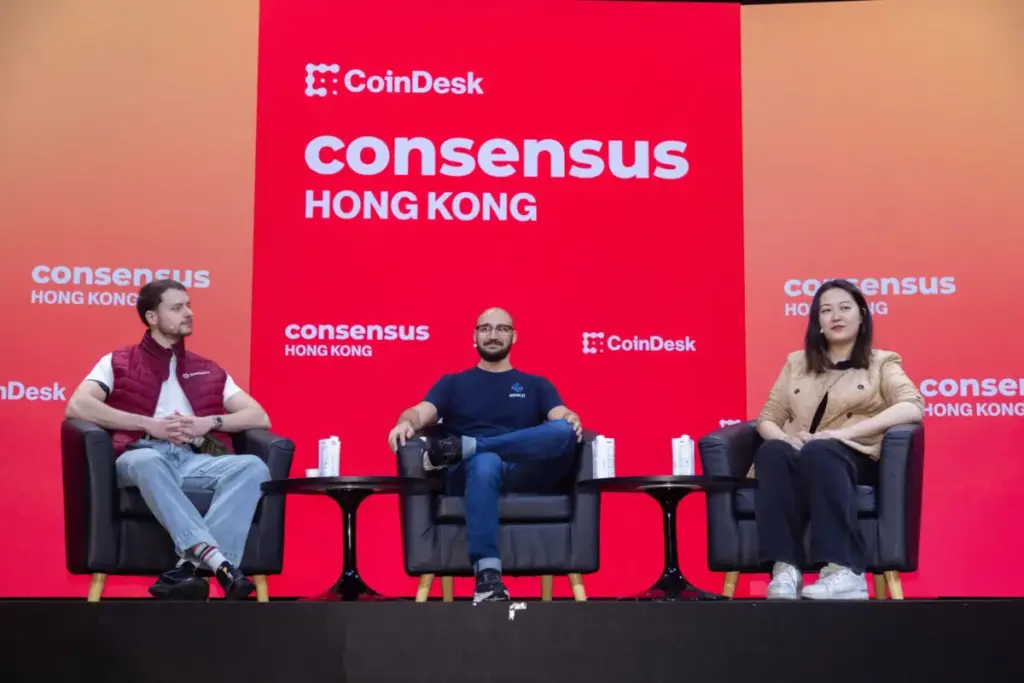
Mike Silagadze, the chief executive officer of ether.fi, frames the pivot as a calculated response to a changing market environment defined by risk and lackluster rewards. "There were no meaningful yield opportunities in restaking and there was some perceived risk from stakers, so we decided it made sense to exit," Silagadze told CoinDesk.
The Reality Behind the Restaking Promise
To understand the scale of this departure, one must look at what restaking was originally designed to accomplish. Standard Ethereum staking allows users to lock up ETH to secure the network, receiving a yield in return. Restaking introduced the concept that this same "locked" ETH could perform a second function. Through EigenLayer, that security could be "rented out" to other services—such as data availability layers and oracles—which would pay for the protection. The allure was twofold: depositors were promised a secondary yield on the same pot of capital. Liquid restaking tokens were created to make this process user-friendly, providing a tradable receipt that could be used as collateral or sold, solving the liquidity constraints of traditional staking.
For a brief window in early 2024, the model seemed unstoppable. Liquid restaking tokens saw growth exceeding 1,000% in just the first six weeks of the year. Yet, the economic model failed to deliver on its core promise. The services purchasing security never generated enough revenue to justify the additional premium required to satisfy stakers, meaning the much-hyped "double yield" largely failed to materialize.
Current data underscores this disparity. As of early September 2026, the restaking category on DefiLlama held approximately $10.02 billion in total value locked (TVL), yet it generated a mere $99,977 in fees over the preceding week. In stark contrast, the liquid staking sector, holding $51.87 billion, pulled in $27.35 million in the same period. By these metrics, standard, non-restaked ETH is earning roughly 53 times more per dollar secured than its restaked counterparts.
Two major developments effectively sounded the death knell for the restaking incentive structure. First, the generous points programs that had subsidized early deposits began to wind down throughout 2025. Second, the implementation of "slashing"—the penalty mechanism that confiscates a portion of staked ETH if an operator misbehaves—went live in April 2025. Suddenly, restaking carried a tangible, priced-in downside risk that was not previously present, yet there was no supplemental yield to compensate for this exposure.
The Impact of Security Failures
Beyond the macroeconomic headwinds, the sector has been plagued by high-profile technical failures. The most damaging incident occurred on April 18, when an attacker exploited the cross-chain bridge used by Kelp, a major competitor in the space. The exploit allowed for the creation of 116,500 rsETH—valued at approximately $293 million—without any underlying ETH backing. The attacker then used these synthetic tokens as collateral on the Aave lending protocol to borrow real ether. The subsequent fallout triggered a massive exodus of liquidity from Aave, leading to estimates of potential bad debt reaching as high as $230 million.
While Silagadze defends the underlying technology of restaking, noting that the Kelp incident was a failure of bridge security rather than the EigenLayer mechanism itself, the psychological impact on the market was profound. "The cause of the Kelp hack was poor security practices with respect to cross-chain, not related to leverage," Silagadze maintained. Nevertheless, for the average depositor, the loss of capital occurred within the "wrapper"—the liquid token itself. By mid-2026, holding these tokens meant assuming additional software risk with no corresponding yield benefit. The wrapper had effectively stopped paying for itself.
A New Strategic Direction: The Crypto Neobank
With the restaking thesis under intense scrutiny, ether.fi has moved to redefine itself as a "crypto neobank." The company is aggressively building out a suite of financial products, including a debit card that allows users to spend against their crypto holdings without triggering a taxable sale, a borrowing market on the Optimism layer-2 network, and a series of curated vaults. In August, the company expanded further by integrating tokenized stocks, metals, and enhanced fiat-to-crypto rails.
Silagadze views this as a vast expansion of the company’s total addressable market, estimating that the traditional neobanking sector generates roughly $300 billion in annual revenue—a figure he notes is 300 times larger than the current DeFi landscape. According to the company, the pivot is already showing results. The ether.fi card grew its share of monthly revenue from 17% in January to 46% in July. "Neobank revenue has fully replaced the revenue lost from restaking and lower ETH price," Silagadze claimed, projecting a 38% increase in overall revenue run rate for the year, despite a 70% decline in core staking and restaking income.
However, independent analysis suggests a more complex picture. Figures from DefiLlama indicate that ether.fi’s gross profit fell by 47% between the third quarter of 2025 and the second quarter of 2026. While both the company’s internal projections and third-party data could technically coexist due to differences in accounting methods—such as the distinction between gross revenue and gross profit—the company has yet to provide full transparency on the basis of its growth claims. Furthermore, there is ongoing debate regarding how cashback rewards are accounted for in these revenue streams, with some analysts arguing that these subsidies inflate volume without necessarily contributing to bottom-line profit.
The Future of Infrastructure
The overarching reality remains that the underlying technology of restaking, such as EigenDA, continues to function on the mainnet. The problem was never the engineering; it was the economic viability of the business model. As the sector matures, even the primary architect of the restaking movement, EigenLayer, has pivoted. Now rebranded as "EigenCloud," the firm is shifting its focus toward verifiable computing, using restaked collateral as a foundation rather than the primary product.
The liquid restaking sector now faces a fundamental identity crisis. As of the second quarter of 2026, the five largest protocols—Renzo, Kelp, Swell, Puffer Finance, and Bedrock—reported a combined gross profit of less than $1 million, a sharp drop from the $2.18 million reported just three quarters prior. Whether this represents a permanent failure of the restaking model or simply a necessary contraction for a sector that was once vastly over-leveraged remains the subject of intense industry debate. For ether.fi, the choice has already been made; the protocol has exited the restaking arena, banking on a future where crypto-native banking services, rather than yield-generation schemes, define the next stage of the industry’s evolution.