In a move that signals a significant shift in the regulatory landscape for digital assets, the U.S. Securities and Exchange Commission (SEC) issued a comprehensive proposal on Thursday aimed at clarifying how investment advisers and regulated funds must handle and safeguard client crypto assets. The 760-page proposal seeks to modernize the oversight of digital holdings, providing a structured, compliant pathway for firms—a development that has been long sought by market participants operating in the previously nebulous "grey area" of federal oversight.
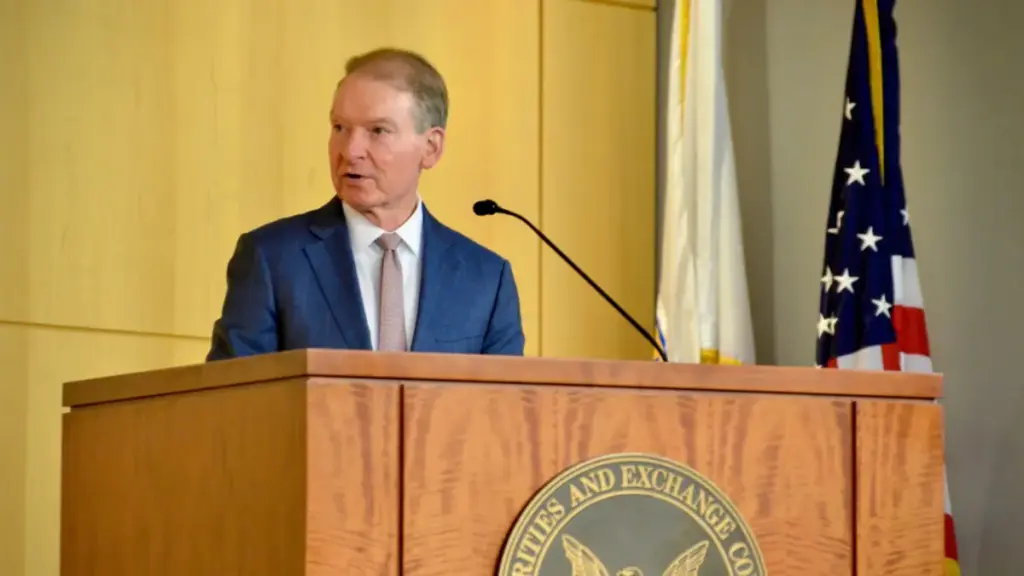
SEC Chairman Paul Atkins, who has been at the forefront of the agency’s recent efforts to reconcile traditional securities law with the realities of blockchain technology, framed the proposal as a vital step toward protecting investors while embracing technological progress. "The proposal would provide a clear regulatory framework for the custody of crypto assets, giving investment advisers and funds a compliant pathway where none existed before—and replacing the grey of uncertainty created by custody rules crafted for a bygone era," Atkins said in an official statement accompanying the release.
Addressing the Custody Gap
For years, the investment management industry has grappled with the limitations of existing custody rules. These regulations, which were largely written to govern traditional assets like stocks, bonds, and cash, were designed to prevent the loss, theft, misuse, or misappropriation of client funds. However, as the digital asset class has expanded into institutional portfolios, the unique technical requirements of holding crypto—such as the management of private keys and the nature of decentralized ledger transactions—have created a mismatch between standard compliance expectations and operational reality.
Atkins emphasized that the status quo was fundamentally unsustainable. "Existing custody rules were designed to protect the assets of advisory clients and regulated funds from loss, theft, misuse, and misappropriation, but they only consider the custody and safekeeping of traditional assets—an untenable situation in the 21st century," he remarked. By proposing this new rule, the SEC is effectively attempting to bridge the gap between 20th-century regulatory logic and the technological infrastructure of the modern financial system.
The proposed framework outlines clear expectations for how investment advisers and regulated funds should manage their records, make federal disclosures, and meet auditing requirements when dealing with crypto assets. Crucially, it defines which types of institutions are qualified to serve as custodians, bringing a degree of legal certainty that market participants hope will encourage greater institutional adoption of digital assets.
The Nuances of "Self-Custody"
One of the more complex aspects of the proposal concerns the potential for advisers to engage in "self-custody" of client crypto assets. It is important to note that the SEC is utilizing this term within the context of institutional asset management, which differs significantly from the colloquial use of "self-custody" by individual retail crypto users.
Under the new proposal, an adviser may be permitted to hold client funds in-house under specific, narrow circumstances. This path is intended to address scenarios where a qualified third-party custodian is not yet available to support a specific digital asset—such as a newly launched token or a highly specialized crypto instrument. However, the regulatory hurdle for such an arrangement is high. An adviser must demonstrate a legitimate inability to find a qualified custodian, and they must possess the necessary technical expertise to secure the assets appropriately.
Furthermore, the SEC has proposed a rigorous oversight mechanism for these instances: an adviser’s ability to self-custody would be subject to a mandatory quarterly review. If a qualified custodian becomes available during that interval, the adviser would be expected to transition the assets to that third party. According to an SEC official, this provision was born out of direct engagement with the industry and the Crypto Task Force, acknowledging that while self-custody would likely remain an "unusual" practice, it provides a necessary safety valve for innovation in the nascent token market.
Regulatory Quorum and the Legacy of the Crypto Task Force
The announcement of these custody rules arrives at a pivotal moment for the Commission, coinciding with the impending departure of Commissioner Hester Peirce. Peirce has been a central figure in the SEC’s approach to digital assets, having led the agency’s inaugural Crypto Task Force since its inception. Her exit on Friday, October 2, marks the end of a significant chapter in the agency’s internal debate over how to balance enforcement with regulatory clarity.
As Peirce departs, the SEC finds itself operating with a lean leadership structure. Earlier this week, the Commission moved to formally reduce the number of commissioners required to form a quorum. Previously, the agency required at least three commissioners to conduct official business; however, under the new policy, that threshold has been lowered to two. The SEC noted that if one of the two remaining commissioners is recused or conflicted from participating in a specific action, the single remaining commissioner is authorized to establish a quorum to proceed.
This change in quorum requirements reflects the agency’s desire to maintain continuity in its rulemaking agenda, even as the composition of the Commission shifts. The advancement of the crypto custody rule, in particular, suggests that the SEC’s momentum on digital asset policy is not expected to stall with the departure of key personnel.
A Completion of the Current Crypto Agenda
With the introduction of the custody proposal, Chairman Atkins has effectively reached a milestone in the SEC’s current crypto-related policy roadmap. This latest action follows a flurry of recent activity aimed at establishing a comprehensive, predictable regulatory environment for blockchain-based finance.
In recent weeks, the Commission released its long-awaited "Innovation Exemption," which outlines specific pathways for firms to tokenize traditional securities products on a blockchain. This initiative was designed to allow established financial products to leverage the efficiency of distributed ledger technology without triggering inadvertent regulatory violations. Additionally, the SEC previously proposed its "Regulation Crypto Asset," a framework that clarifies how digital asset issuers can navigate federal fundraising rules, effectively creating a "roadmap to compliance" for projects that seek to raise capital while providing transparency to investors.
The custody rule proposal is now open for a 60-day public comment period. During this time, the SEC is expected to field feedback from a wide array of stakeholders, including traditional asset managers, crypto-native custodians, legal experts, and investor advocacy groups. The input gathered during this period will be critical in refining the final rule, as the agency seeks to balance the objective of investor protection with the desire to foster a stable, competitive, and innovative financial market.
As the Commission moves forward, the focus will likely shift from the proposal stage to the implementation and enforcement of these new standards. For now, the investment industry is left to digest the 760-page document, which serves as the most comprehensive effort yet to codify the role of crypto assets within the regulated U.S. financial system. The coming months will be telling as the industry determines how to align its operations with these new federal expectations, marking a definitive evolution in the relationship between Wall Street and the world of digital assets.