










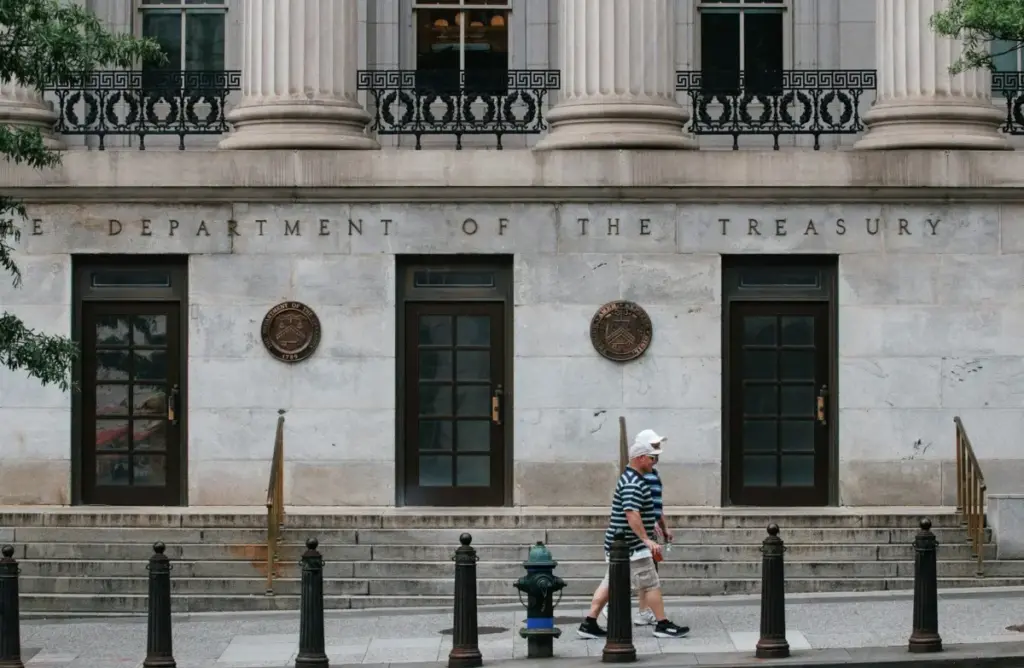
In a significant policy pivot, the U.S. Treasury Department has officially scrapped a pair of high-profile regulatory proposals that had lingered in limbo for years, marking a notable shift in the government’s approach to digital asset oversight. The Financial Crimes Enforcement Network (FinCEN), the Treasury bureau responsible for safeguarding the financial system against illicit use, announced on Sunday the withdrawal of rules that would have imposed stringent reporting requirements on crypto-asset transactions. These abandoned proposals—one concerning "unhosted" digital wallets and another targeting cryptocurrency mixing services—had been subjects of intense debate within the financial technology sector, yet neither had ever been formally implemented.
The withdrawal of these measures is being characterized by the agency as part of a broader Trump administration mandate to pursue a deregulatory agenda, aimed at streamlining federal oversight and ensuring that digital asset regulations are "fit-for-purpose." By removing these long-standing, unresolved proposals from the regulatory docket, the Treasury is effectively closing the book on initiatives that had created years of uncertainty for banks, crypto exchanges, and individual investors who manage their own digital assets.
The Unhosted Wallet Proposal: A Legacy of the 2020 Regulatory Push
The more prominent of the two withdrawn rules originated in December 2020, during the final weeks of the first Trump administration. At the time, the Treasury Department moved rapidly to introduce a rule that would have forced financial institutions—including traditional banks and money-service businesses like cryptocurrency exchanges—to collect and report specific identifying information whenever a customer transferred significant amounts of cryptocurrency to a self-custodied wallet.
In the parlance of the crypto industry, an "unhosted" or "self-custodied" wallet refers to a digital storage solution where an individual, rather than a centralized intermediary, maintains direct control over the private cryptographic keys. Because these wallets operate outside the purview of traditional financial institutions, regulators have long viewed them as potential blind spots for anti-money laundering (AML) and counter-terrorist financing (CTF) efforts.
Under the 2020 proposal, banks and crypto platforms would have been required to file a report with FinCEN if a customer transferred more than $10,000 worth of crypto to or from an unhosted wallet. Crucially, the rule included an "aggregation" clause; firms would have been responsible for tracking transactions that crossed the $10,000 threshold when added together over a 24-hour period. Furthermore, the regulation would have required these entities to gather and report sensitive information regarding both the customer initiating the transfer and the recipient of the funds on the other side of the transaction.
For the cryptocurrency community, the proposal was seen as a direct challenge to the ethos of digital sovereignty. Critics argued that the compliance costs would be prohibitive for smaller firms and that the technical requirements were overly burdensome, if not impossible, to implement given the decentralized nature of blockchain technology. The proposal sparked a massive wave of public feedback, drawing thousands of comments from privacy advocates, developers, and industry trade groups. Despite the intensity of the debate, the rule remained in a state of regulatory purgatory for nearly six years, neither fully enacted nor formally discarded, leaving the industry in a state of perpetual anticipation regarding when—or if—the government would move to enforce such measures.
Reversing Course on Crypto Mixing Regulations
In addition to the unhosted wallet rule, FinCEN also announced the withdrawal of a more recent 2023 proposal that sought to address the use of crypto "mixers." Mixing services, or tumblers, are tools designed to obscure the trail of digital asset transactions by pooling funds from multiple users and redistributing them, thereby making it significantly more difficult for investigators to trace the origin and destination of the assets.
The 2023 proposal would have classified transactions involving crypto mixing as a category of "primary money-laundering concern." By designating them as such, the government intended to grant itself the authority to impose mandatory, enhanced reporting requirements on any financial institution that handled these types of transactions. The move was part of an aggressive push by federal authorities to curb the use of mixers, which have been frequently cited by the Treasury and the Department of Justice as preferred vehicles for ransomware groups, North Korean state-sponsored hackers, and other illicit actors attempting to launder stolen funds.
By withdrawing this proposal, the Treasury is signaling a retreat from a blanket regulatory approach toward these privacy-enhancing technologies. The decision suggests a shift in focus toward more targeted enforcement actions against specific bad actors, rather than the implementation of broad, sector-wide reporting mandates that would affect all financial institutions handling crypto-assets.
A Strategic Shift Toward "Fit-for-Purpose" Regulation
The decision to strike these two proposals from the books is reflective of the broader "deregulatory agenda" currently being championed by the Trump administration. The Treasury Department emphasized that the withdrawals were necessary to "clean up" the regulatory landscape, arguing that many of the proposed rules from previous years were either outdated, overly prescriptive, or misaligned with the rapid technological evolution of the digital asset market.
The term "fit-for-purpose" is increasingly being used by federal policymakers to describe a regulatory framework that balances the need to prevent financial crimes with the necessity of fostering innovation. By pruning away legacy proposals that lacked consensus or practical viability, the administration appears to be attempting to reset the relationship between the government and the burgeoning crypto industry.
For the financial institutions that would have been responsible for enforcing these rules, the withdrawal comes as a significant relief. Compliance departments have spent years preparing for the possibility that the 2020 and 2023 rules might suddenly go into effect. The reporting requirements—particularly the mandate to identify the owners of unhosted wallets—would have necessitated deep changes to the underlying infrastructure of many exchanges and custodial services. The administrative burden of tracking 24-hour aggregate volumes and verifying the identity of counterparties on the blockchain would have been a massive undertaking, likely requiring significant investment in blockchain analytics software and additional personnel.
Implications for the Digital Asset Ecosystem
The impact of this policy shift extends beyond just the reduction of compliance costs. It also signals a potential shift in how the U.S. government views the role of self-custody in the broader financial system. Proponents of digital assets have long argued that the ability to hold one’s own keys is a fundamental right and a core feature of cryptocurrency that should not be hindered by traditional banking-style reporting mandates. By choosing not to pursue the unhosted wallet reporting rule, the Treasury is effectively acknowledging the practical and ideological difficulties of forcing a decentralized technology into a centralized regulatory box.
However, the withdrawal of these specific proposals does not mean that the Treasury is abandoning the fight against money laundering. FinCEN maintains that it remains committed to ensuring that digital assets are not used to undermine the integrity of the U.S. financial system. Instead, the move suggests a change in tactics. Rather than relying on rigid, industry-wide reporting mandates that were drafted years ago, the agency may be leaning toward more surgical, intelligence-led enforcement. This approach would focus on identifying and penalizing specific illicit actors who use crypto for illegal purposes, rather than imposing blanket requirements that impact the entire ecosystem of legitimate users and businesses.
As the industry digests the news, the long-term impact of these withdrawals remains to be seen. The regulatory landscape for digital assets continues to evolve, and while these two specific hurdles have been cleared, the broader question of how to govern a borderless, decentralized asset class remains at the forefront of the financial policy debate. For now, the Treasury’s decision serves as a definitive end to a long-running chapter of uncertainty, providing a clearer, if more sparse, regulatory environment for the stakeholders involved in the digital asset space. The withdrawal of these rules marks a rare instance of federal regulators walking back major initiatives, underscoring the influence of the current administration’s focus on reducing the federal footprint and recalibrating the oversight of the rapidly expanding crypto economy.