







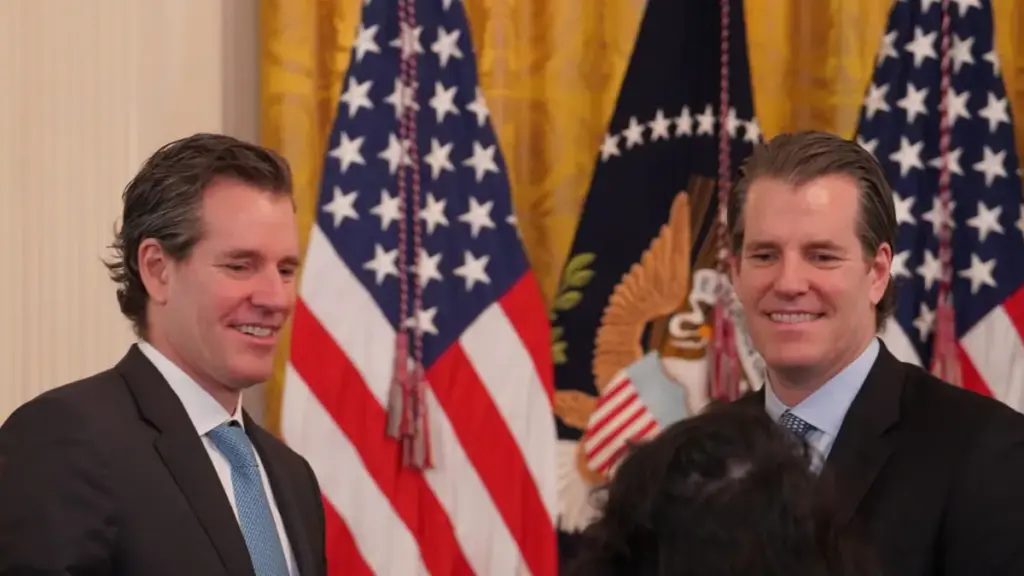
The crypto landscape is undergoing a period of intense consolidation, and few entities have found themselves under the microscope quite like Gemini Space Station (GEMI). As the platform’s stock price has plummeted roughly 80% from its initial public offering, industry analysts and market observers are increasingly raising the question of whether the exchange, founded by billionaire entrepreneurs Cameron and Tyler Winklevoss, is becoming an inevitable acquisition target.
The market value of the platform has shriveled to approximately $753 million, a staggering drop from its peak valuation of roughly $4 billion. This dramatic contraction has shifted the narrative surrounding the company. Where investors once looked at Gemini as a standalone titan of the crypto industry, the current conversation has pivoted to its potential utility as a strategic asset for a larger firm. The platform’s shrinking spot-trading business is being viewed through a new lens: not as a failed enterprise, but as a shell containing high-value regulatory licenses, robust custody infrastructure, and an established, albeit thinning, customer base.
The Logic of Consolidation
The spark for the most recent wave of speculation came from Lorenzo Valente, the director of digital assets research at ARK Invest. In a post on X last month, Valente proposed that Hyperliquid, the offshore perpetual-trading platform, should consider an acquisition of Gemini. The strategic rationale, according to Valente, lies in the potential for Gemini to serve as a regulated U.S. gateway for perpetual futures and prediction markets—sectors that are currently booming but remain fraught with regulatory complexity.
For a platform like Hyperliquid, which operates offshore, the ability to "plug in" to the U.S. market via a pre-approved entity could save years of legal wrangling and the exorbitant costs associated with securing state-by-state money transmitter licenses and other federal compliance approvals. The presence of the Winklevoss twins, who hold concentrated voting control, could, theoretically, make the mechanics of such a deal more straightforward than navigating a fragmented shareholder base.
While there is currently no evidence that Hyperliquid is actively pursuing a deal, the proposal highlights a fundamental shift in how crypto mergers and acquisitions are valued. In the early days of the industry, acquisitions were often driven by the desire to capture trading volume or user numbers. Today, buyers are increasingly hunting for "regulatory moats"—the hard-won licenses and institutional trust that established exchanges have cultivated over years of operation.
A Shrinking Exchange Business
The urgency behind these discussions is driven by the stark reality of Gemini’s financial performance. According to the company’s second-quarter 2026 results, the exchange’s revenue fell 38% year-over-year to $12.5 million. The decline in trading activity is even more pronounced; spot trading volume cratered by 66%, falling to $3.8 billion. Perhaps most tellingly for a platform reliant on holding client assets, the total assets under custody on the platform dropped from $18.2 billion to $8.4 billion.
These figures paint a picture of a business that is struggling to maintain its relevance in an increasingly crowded and competitive marketplace. Venture capital investors speaking on the condition of anonymity have noted that Gemini’s core exchange technology, while functional, offers limited differentiation from more nimble or lower-fee rivals. In a market where retail traders are highly sensitive to fee structures and institutional players demand deep liquidity, Gemini has struggled to maintain its historical dominance.
However, the value of the "shell" remains. An institutional investor pointed out that the cost of building a similar regulatory infrastructure from scratch is not merely financial—it is a matter of time and human capital. For a foreign firm or a traditional finance institution looking to enter the U.S. crypto space, buying Gemini is effectively a shortcut. It allows the acquirer to bypass the arduous process of obtaining regulatory approvals, which can take years of intensive interaction with agencies like the SEC and various state regulators.
A Broader Pattern of M&A Activity
Gemini’s situation is far from unique; it is part of a broader trend of consolidation across the digital asset sector. As the industry matures, companies are choosing to grow through acquisition rather than through organic development.
In July, the digital-asset services firm Keyrock acquired the trading assets of BlockFills. This deal was not about absorbing a failing competitor, but rather about integrating BlockFills’ regulatory licenses and institutional client relationships into Keyrock’s existing operations. Similarly, the tokenization firm Ondo has been exploring potential acquisitions valued at as much as $500 million to bolster its market position. Other industry stalwarts, including LMAX and the market maker B2C2, have held discussions regarding strategic sales or partnerships, further signaling that the era of the independent, mid-sized crypto firm may be giving way to a more consolidated landscape dominated by larger, diversified players.
Reports from April suggested that potential buyers had already begun circling Gemini, though the interest was focused specifically on the company’s shuttered European and U.K. operations. The primary motivation in those instances was, once again, the acquisition of regulatory licenses that would allow a buyer to operate in those jurisdictions without undergoing the lengthy application process. While those specific discussions have not yet yielded a deal—largely due to disagreements over valuation—the fact that such conversations are happening at all suggests that the market recognizes the latent value in Gemini’s regulatory footprint.
The Hurdle of Ownership
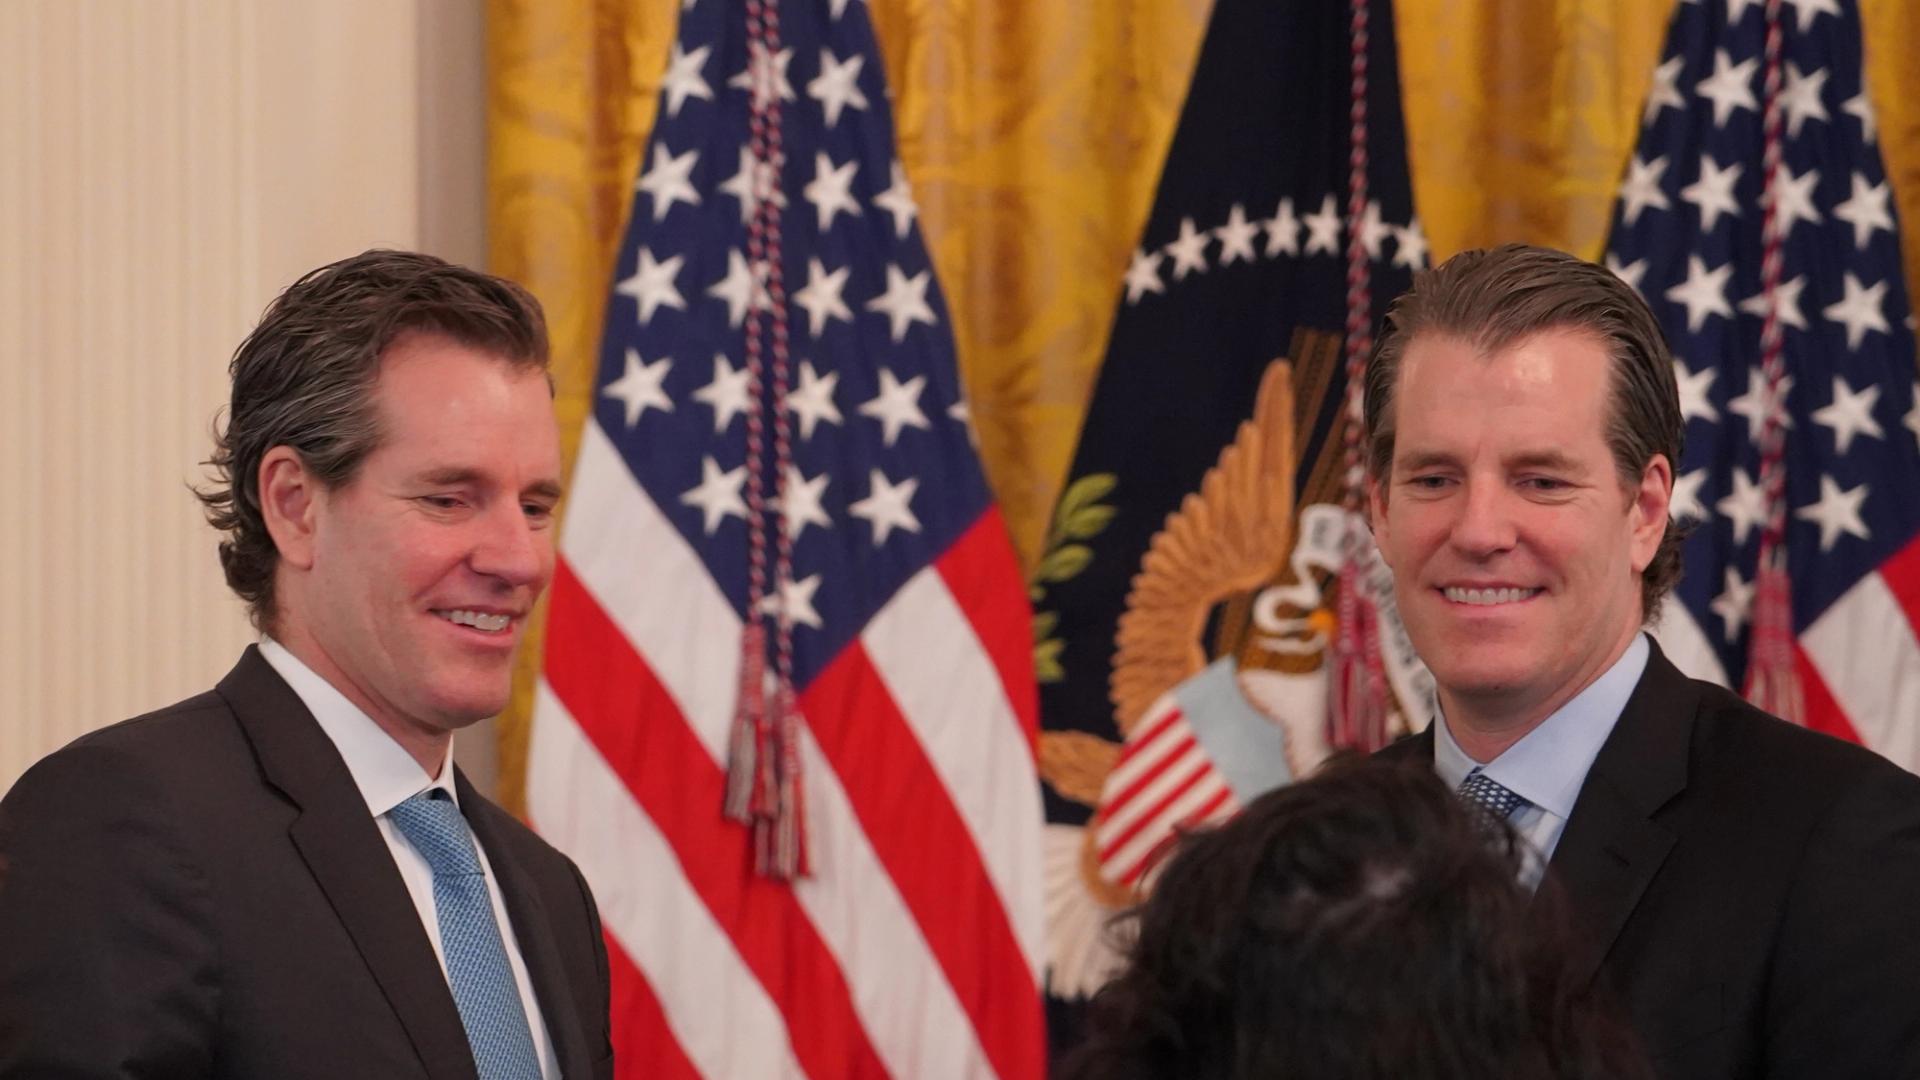
Any discussion regarding the acquisition of Gemini must eventually contend with the reality of its ownership structure. The Winklevoss twins maintain a tight grip on the company, holding approximately 94.5% of its voting power.
This structure is a double-edged sword for a potential suitor. On one hand, it simplifies the negotiation process. An acquirer does not need to build a coalition of institutional shareholders or lobby a diverse board of directors; they only need to convince two individuals. If the brothers decide that the time is right to exit or to pivot the company into a new ownership structure, a deal could theoretically be finalized with relative speed.
On the other hand, this concentration of power makes a hostile takeover impossible. There is no path for activist investors to force a sale if the founders remain committed to their current vision or if they disagree with the valuation offered by potential buyers. The brothers’ firm control means that the decision to sell rests entirely on their assessment of the platform’s future prospects versus the reality of its current decline.
As the crypto industry continues to evolve, the question remains: do the Winklevoss twins view Gemini as a long-term asset that can be turned around, or are they open to the possibility that the platform’s greatest value now lies in its sale to an entity better equipped to navigate the current market? For now, the exchange remains in a state of limbo, with its shrinking financial metrics acting as a siren song for those who see the company not as it is, but as a gateway to the broader, regulated future of digital assets. Whether the twins will be swayed by the cooling market or continue to steer the ship remains the central uncertainty in one of the most closely watched stories in the crypto economy.